Put yours on first
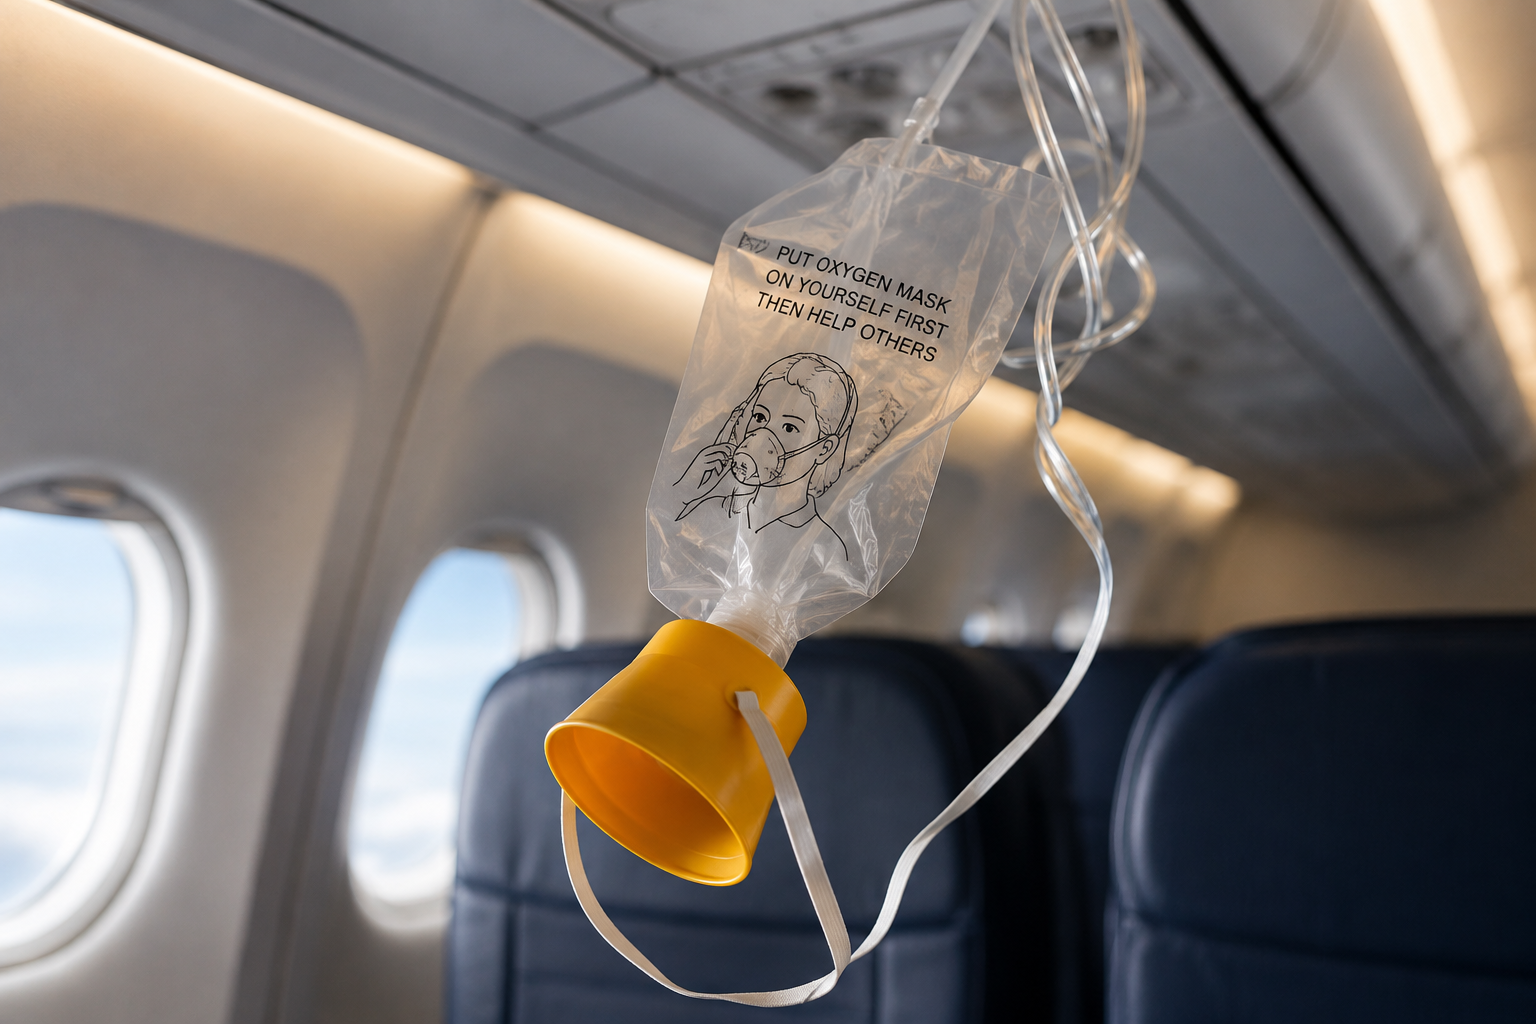
There is a familiar instruction given on every plane before take-off: “In the event of an emergency, put your own oxygen mask on before helping others.”
It sounds slightly selfish, particularly if you are travelling with children, but there is a very good reason for it. If you run out of oxygen, you are no longer in a position to help anyone else.
The same principle applies to your finances.
As parents, it is natural to want to help our children. We want to give them the best possible start, help them buy their first home, support them through university, contribute towards a wedding, or provide a financial safety net when they need it.
But sometimes, in trying to help our children financially, we can put our own financial security at risk.
Your retirement comes first
One of the biggest financial mistakes parents can make is prioritising their children's financial future at the expense of their own.
Your children have something you don't: time.
A 25-year-old who receives less financial assistance today has decades to build their income, savings and investments. You may have a much shorter timeframe to build the funds you will need to support yourself through retirement.
For example, helping a child with a $100,000 deposit might feel like an excellent investment in their future. But if providing that money means you have to delay retirement, reduce your lifestyle or rely on your children financially later in life, the decision may ultimately create a problem rather than solve one.
The best gift you can give your children may be not becoming financially dependent on them.
That doesn't mean you shouldn't help
Putting your own oxygen mask on first doesn't mean saying no to your children.
It means making sure you understand what you can afford to give without compromising your own financial security.
Before providing significant financial assistance, consider:
Can I afford this without affecting my retirement plans?
Will I still have enough money and investments to maintain my lifestyle?
What happens if I live longer than expected?
Could unexpected costs, such as healthcare or aged care, change the picture?
Am I helping my child become financially independent, or simply delaying a problem?
Are there other ways I can help that don't involve a large financial gift?
There can also be important implications around gifting, ownership, family relationships and estate planning. What seems straightforward today can become more complicated later.
Financial independence works both ways
Helping your children financially is often an expression of love. But financial independence is also a form of security for you and for them.
A good financial plan should allow you to enjoy your retirement, deal with unexpected expenses and remain in control of your financial decisions, while still giving you the flexibility to help your family when you genuinely can.
So, before you reach for your wallet to help the next generation, take a moment to check your own oxygen supply and put your own financial mask on first.
Once you know that your retirement and long-term financial security are on track, you can help your children from a position of strength rather than putting your own future at risk.